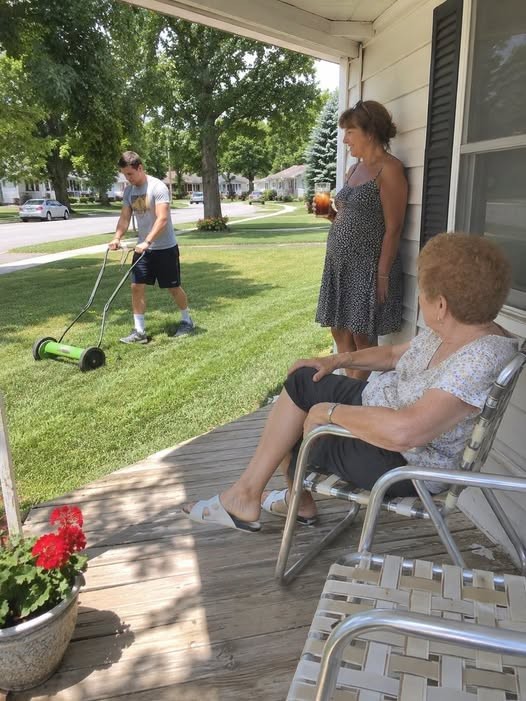

My Uncle Took Money From Grandmas Social Security Just to Cut Her Grass but When I Came Home From Deployment Everything Changed
Editor’s note: The supplied draft presents only a brief, first-person story opening and does not provide names, dates, locations, records, or independently verifiable evidence. It therefore cannot be treated as a confirmed account of wrongdoing by any individual. This article uses the premise as an opportunity to explain, in factual terms, how families can recognize and address possible financial exploitation of older adults while respecting independence, privacy, and due process.

Why Questions About an Older Relative’s Money Matter
A checkbook left on a kitchen table can sometimes raise difficult questions. A family member may notice recurring payments, unexplained withdrawals, or charges that appear unusually high for ordinary services such as lawn care, transportation, housekeeping, or home repairs. These discoveries can be emotionally charged, particularly when relatives have different views about what assistance is needed and what compensation is fair.
It is important, however, not to jump immediately to conclusions. Older adults have the right to make their own financial decisions when they have the capacity to do so. They may choose to pay relatives for practical help, give gifts, or support loved ones. A payment that appears unusual to one relative may have been discussed and agreed upon by the older person.
At the same time, financial exploitation is a serious concern. The U.S. Consumer Financial Protection Bureau describes elder financial exploitation broadly as the illegal or improper use of an older person’s money, property, or other resources. It can involve deception, pressure, misuse of a power of attorney, unauthorized account access, or taking funds without consent. It may also occur within families, which can make it especially difficult to identify and discuss.
Understanding Social Security Benefits and Representative Payees
For many older Americans, Social Security retirement, survivors, or disability benefits are a central part of household income. The Social Security Administration generally pays benefits directly to the recipient, often through direct deposit. Recipients can use their benefits for everyday needs, including food, housing, utilities, health care, personal care, and services that help them remain safely at home.
In some circumstances, the Social Security Administration appoints a representative payee to receive and manage benefits for a person who cannot manage or direct the management of their own money. A representative payee is not free to use the funds as they wish. The payee’s responsibility is to use benefits for the beneficiary’s current needs and, where possible, to save any remaining funds for the beneficiary.
The role requires careful stewardship. Representative payees must keep records, report certain changes to the Social Security Administration, and ensure that benefit payments are used in the beneficiary’s best interest. Family members who have concerns about how a representative payee is managing funds may contact the Social Security Administration to ask about reporting options and review procedures.
When Payments for Family Help Are Appropriate
Family caregiving often includes tasks that would otherwise require paid services. A relative may mow the lawn, make grocery trips, prepare meals, provide transportation, help with household maintenance, or coordinate appointments. These contributions can be substantial, and some families choose to compensate the caregiver.
Compensation is not inherently improper. Clear communication is the key. If an older adult wishes to pay a relative for lawn care or other work, families can reduce confusion by creating a simple written arrangement. The document may identify the work being performed, the expected schedule, the amount to be paid, and whether the arrangement can be changed or ended. Receipts, invoices, or a basic payment log can also help preserve transparency.
Such records protect everyone involved. They help the older adult understand where money is going, acknowledge the caregiver’s labor, and give other relatives a factual basis for discussion rather than relying on assumptions. If the person has a financial adviser, attorney, trusted friend, or designated agent under a power of attorney, that individual may also be able to help establish appropriate oversight.
Potential Warning Signs of Financial Exploitation
No single sign proves exploitation. Still, consumer-protection agencies encourage families, financial institutions, and caregivers to pay attention to changes that do not fit an older person’s usual habits, preferences, or financial circumstances. Concerns may warrant a calm conversation or professional guidance when there are unexplained withdrawals, new account users, sudden changes to legal documents, missing financial statements, or unusual purchases.
Other possible signs include unpaid bills despite sufficient income, a sudden inability to access bank accounts, isolation from trusted friends or relatives, or pressure to sign documents that have not been fully explained. A person may also seem anxious, confused, or reluctant to discuss financial matters in the presence of a particular individual.
These signs need context. Cognitive changes, grief, illness, and changes in living arrangements can complicate financial management without necessarily indicating misconduct. The appropriate response is to gather information carefully, prioritize the older adult’s safety and preferences, and avoid public accusations that could cause harm or divide a family unnecessarily.
How to Start a Respectful Conversation
When an adult child, grandchild, or other relative has concerns, a private and respectful conversation with the older person is often the best first step. Rather than beginning with an accusation, ask open questions: “Would you like help reviewing your bills?” “Do you feel comfortable with the people who assist you?” “Would you like us to make a list of the services you pay for each month?”
Older adults should be included in decisions to the greatest extent possible. Their autonomy matters. If they say they willingly paid for a service and understand the amount, that preference should be taken seriously. If they are uncertain about transactions or say they felt pressured, the situation may require further support.
Families can also suggest practical safeguards without taking control away from the older person. These may include automatic bill payments, account alerts, a trusted contact person at a financial institution, direct deposit, secure storage for checkbooks, and regular reviews of bank statements. The CFPB notes that a trusted contact is someone a financial institution may contact in limited circumstances if it cannot reach the account holder or has concerns about possible exploitation.
What to Do if You Suspect Improper Use of Funds
If there is an immediate concern that an older person is being pressured, deprived of necessities, or prevented from accessing money, families should seek help promptly through local adult protective services, law enforcement, or emergency services when appropriate. Adult Protective Services programs operate at the state level in the United States and investigate reports involving vulnerable adults, although procedures vary by jurisdiction.
For concerns involving Social Security payments or a representative payee, the Social Security Administration provides guidance on reporting suspected misuse. A person can contact the agency directly and provide factual details, such as dates, amounts, account information where relevant, and the beneficiary’s current needs. Reporting should focus on evidence and specific observations rather than speculation.
Concerns involving bank accounts, credit cards, or suspected fraud may also be reported to the relevant financial institution. Banks and credit unions have processes for reviewing unusual activity, and consumers may ask what protections or account-monitoring options are available. The Federal Trade Commission’s consumer reporting system is another resource for reporting fraud and seeking information about recovery steps.
Legal advice can be useful when the matter involves a power of attorney, property title, a caregiver agreement, guardianship, or a dispute about capacity. An attorney experienced in elder law can explain local rules and help families choose options that protect the older adult’s rights. The Eldercare Locator, a public service of the U.S. Administration for Community Living, can help connect people with local aging services.
Deployment, Family Separation, and Returning Home
The story premise also reflects a broader reality for military families: deployments can create distance from household events and financial decisions. Service members may return home to find that a relative’s health, living arrangements, or support needs have changed. Re-entry can bring relief, but it can also uncover unresolved family tensions.
Military families can reduce uncertainty by discussing caregiving plans before or during a deployment whenever possible. A plan may identify who will check in on an older relative, who is authorized to communicate with health providers or financial institutions, how expenses will be documented, and whom to contact if concerns arise. These conversations are not always easy, but they can prevent misunderstandings later.
Veterans, active-duty personnel, and their families may also seek practical guidance through military family-support programs, legal assistance offices where available, and local aging-services organizations. The central goal should be the same: ensuring that an older loved one is safe, financially secure, and treated with dignity.
Building Transparency Without Creating Conflict
Financial questions can damage relationships when family members feel excluded, mistrusted, or unfairly blamed. A constructive approach focuses on systems rather than personalities. Instead of asking who is at fault, families can ask what records exist, what services are needed, what the older person wants, and what safeguards would make everyone more comfortable.
A monthly review can be useful. This does not need to be complicated: income, recurring bills, caregiver payments, major purchases, and outstanding needs can be listed in plain language. The older adult should participate whenever possible. If several relatives are involved in care, shared documentation can prevent one person from bearing all responsibility or suspicion.
Independent professionals may help when conflict is persistent. A social worker, geriatric care manager, elder-law attorney, financial counselor, or mediator can provide a more neutral perspective. Their role is not to decide family disputes based on rumor, but to help clarify responsibilities and protect the well-being of the older adult.
Protecting Dignity Is the Central Priority
Stories about a grandparent’s checkbook can evoke understandable concern, especially when money is limited and family trust is uncertain. Yet every situation deserves care, evidence, and respect. Paying a relative for help may be a reasonable choice. Improper use of an older adult’s resources, by contrast, should be addressed through appropriate reporting channels and professional support.
The most effective response combines compassion with practical safeguards: listen to the older person, document financial arrangements, seek clarification before making allegations, and act quickly if there are credible signs that someone’s basic needs or financial security are at risk. These steps can help families protect both a loved one’s independence and the resources they have worked a lifetime to earn.
Sources
- Social Security Administration: Representative Payee Program
- Social Security Administration: Reporting Fraud, Waste, and Abuse
- Consumer Financial Protection Bureau: Elder Financial Protection
- Administration for Community Living: Eldercare Locator
- Federal Trade Commission: ReportFraud.ftc.gov
- National Council on Aging: Elder Financial Exploitation Information
Disclaimer: This content is intended for entertainment purposes only and is not based on real events.